When the US Treasury curve inverts—short‑term yields rising above long‑term yields—it doesn’t just spook bond investors. It quietly rewrites how equity sectors trade, including semiconductors. An inverted curve is a signal about future growth, funding costs, and recession risk. Semi stocks, with their mix of cyclical exposure and long‑duration growth narratives, respond in distinct ways. Within the sector, “style” rotation—between growth vs value, large vs small, equipment vs device makers—often emerges as investors reposition for a different macro regime.
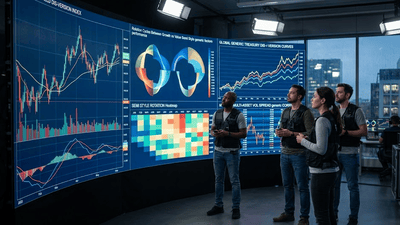
This post explores semi style rotation patterns during Treasury curve inversion periods, through the macro linkages of interest rates, exchange rates, credit, and commodities. The aim is to be flexible and polished, because inversion periods themselves are nuanced: sometimes they precede recessions, sometimes they don’t, but they almost always shift how risk is taken in semis.
What a Treasury Curve Inversion Signals
A Treasury curve inversion—commonly tracked as the 2‑year yield above the 10‑year yield or the 3‑month above the 10‑year—signals that:
- Markets expect future growth to slow or policy to eventually ease.
-
In macro terms:
- Central banks have likely raised rates aggressively; real yields may be elevated.
Interest Rates and Duration: Growth vs Value Within Semis
Curve inversion is fundamentally about rates. In semis, rate dynamics show up as duration risk—how sensitive different styles are to changes in discount rates:
-
-
Mature, cash‑generating companies—commodity memory, diversified IDMs, established analog makers—may offer higher FCF yields, looking more attractive when rates are high and curves inverted.
Style rotation pattern:
Exchange Rates: Global Semis and Regional Style Tilts
Curve inversion periods often coincide with changes in FX dynamics, particularly a stronger dollar:
Style rotation tied to FX can look like:
-
During inversion and strong‑dollar phases, global funds may overweight US semi giants and underweight smaller, FX‑exposed names elsewhere. -
Small cap semis that rely on weaker currencies or local funding may be viewed as higher risk.
Thus, curve inversion can drive style rotation not just between growth and value, but between
Credit Conditions: Leverage and Balance Sheet Style
Curve inversion also interacts with credit spreads and bank lending standards:
Style rotation pattern:
-
Funds shift from semis with high debt and aggressive capex to those with net cash and conservative funding profiles. -
Larger firms with diversified funding sources and better access to capital markets gain relative favour.
Commodities and Industrial Cycles: Equipment vs Device Makers
Semis are tied to industrial cycles and commodity trends, which often shift around curve inversion periods:
Style rotation pattern:
-
In inversion periods, funds may reallocate from equipment suppliers (highly cyclical, capex‑dependent) to semis whose demand drivers are seen as more resilient (data center, AI infrastructure, certain automotive chips). -
Within both equipment and devices, names tied to secular trends (AI, electrification, advanced power management) may retain allocation even as more cyclical sub‑segments are trimmed.
Commodities and industrial activity thus influence semi style: inversion periods with weakening industrial indicators encourage rotation away from pure cycle plays toward secular exposure.
Putting It Together: Stylized Style Rotations in an Inversion
Combining these macro linkages, we can sketch a stylized semi style rotation pattern across the life of a curve inversion:
Phase 1: Initial Inversion – Signal, Not Yet Pain
Investors see the inversion as a
Phase 2: Persistent Inversion – Late-Cycle Behaviour
In this phase, style rotation becomes more pronounced. Funds reposition for a potential recession or slowdown while maintaining exposure to long‑term tech themes.
Phase 3: Inversion Ending – Policy Turn and Repricing
Here, semi style rotation can reverse: growth and higher beta styles receive fresh capital, while the value and quality overlay remains in the background as a risk anchor.
Investor Takeaways: Using Inversion Periods as Style Signals
For semi investors, recognizing these patterns offers several practical takeaways:
-
A curve inversion is not a precise timer, but it is a meaningful late‑cycle indicator. Style tilts toward quality and FCF yield in semis align with this risk profile. -
The extent of rotation should depend on how rates, FX, credit, and commodities evolve. A benign inversion (soft landing) might justify limited rotation; a stressed inversion (credit tightening) calls for deeper adjustments. -
Not all semis are equal. Different sub‑segments (equipment, logic, memory, analog) respond differently to macro regimes; style decisions should be calibrated at that level. -
Style rotation is not a one‑way move. As inversion periods evolve and policy signals change, it may be appropriate to move back toward growth styles or cyclical exposures.
In other words, treat curve inversion as a
Closing Thoughts: Reading the Curve, Rotating the Styles
“Semi Style Rotation Patterns During the Treasury Curve Inversion Period” is about translating a macro signal into sector‑level action. An inverted curve is a message about the future: funding costs, growth risks, and potential policy shifts. Semiconductors, sitting at the heart of both the industrial cycle and the tech narrative, react to that message through style rotation—between growth and value, large cap and small cap, equipment and device makers.
By linking interest rates, exchange rates, credit, and commodities to these rotations, investors can avoid treating semis as a monolithic bet and instead actively manage which styles they own in different phases of the inversion. The yield curve can’t tell you which chip will win the next design slot, but it can help you decide whether to own that chip through a high‑beta growth name or a steady cash‑rich incumbent. In late‑cycle environments, that distinction often matters as much as the technology itself.